Most advertised lease payments assume top-tier credit, which commonly starts around 720, but there is no universal minimum credit score to lease a car. Each lender sets its own tiers. Experian suggests 670 or higher, and lenders may prefer 700 or more; people lease with lower scores by paying a higher money factor or more due at signing.
Quick facts
Every deal on this month's lease specials is quoted at $3,000 due at signing, tax excluded, so you know the payment you are aiming for.
No: Experian states there is no standard credit score needed to lease a car, and no California statute sets one.
What exists instead is a ladder of tiers, and each lender decides where its tiers start and what money factor each pays.
The score they use is usually not the one on your banking app: myFICO says FICO Auto Scores, which run from 250 to 900, decide most auto financing, and Experian notes they weigh past car payments more heavily. Experian adds that one application may go to several lenders using different scores, so the same 740 can land in different tiers.
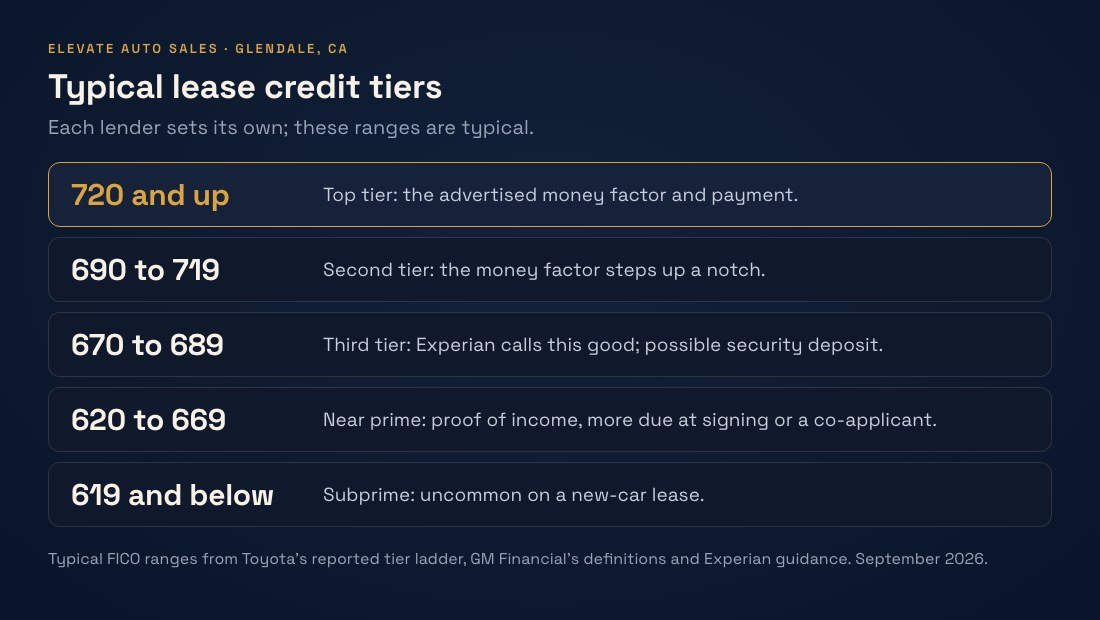
Top tier commonly starts around 720 at captive lenders, the manufacturers' finance arms (Toyota's reported ladder, echoed by broker reports for other captives), but every range here is typical, not universal, because each lender sets its own.
| Typical tier | Typical FICO range | What it usually means for a lease |
|---|---|---|
| Top tier | 720 and up | The advertised money factor and payment. |
| Second tier | 690 to 719 | The money factor steps up a notch. |
| Third tier | 670 to 689 | The low end of what Experian calls good; a higher money factor and sometimes a security deposit. |
| Near prime | 620 to 669 (GM Financial: 620 to 679) | GM Financial's near prime band overlaps the tier above; it says lenders may ask for proof of income or more due at signing, and Experian suggests a co-signer at this level. |
| Subprime (GM Financial: below 620) | 619 and below | Uncommon on a new-car lease; GM Financial says expect higher down payments and more paperwork. |
Whatever your score says, the credit application takes a few minutes and tells us which tier lenders actually place you in.
On the example lease below, a money factor 0.001 higher (2.4 points of APR, since money factor times 2,400 is the APR) costs $59.20 a month, because rent charge equals the money factor times the sum of adjusted capitalized cost and residual.
Example, not a quote: a $40,000 car, an adjusted capitalized cost of $36,000, a residual of $23,200 (58% of MSRP), 36 months, tax excluded.
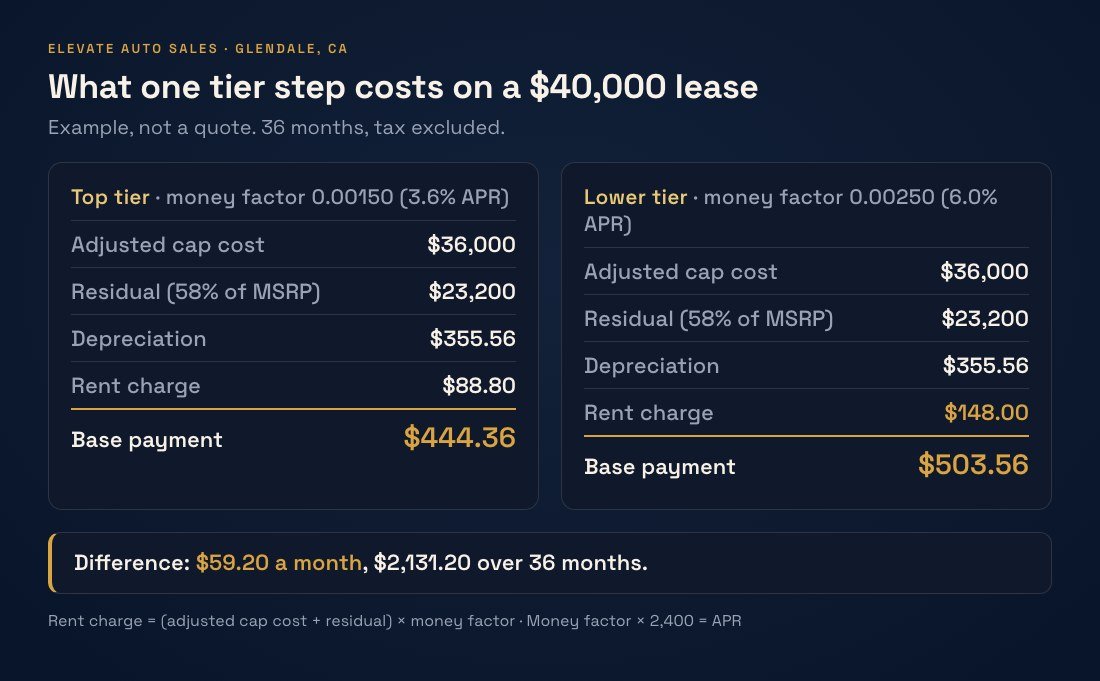
Tax is added on top at your city's rate, which rises in Los Angeles County on October 1, 2026; our LA County sales tax increase post has your city. Send us your city and model through Request a car and we will quote it for your tier.
Lenders approve a file, not a number: income, existing debts, history length, past car payments and recent applications all move the decision and the tier.
Below top tier, expect to show income. GM Financial lists a pay stub, proof of residency such as a utility bill, and personal references among documents a lender may request; a W-2 or 1099, or bank statements and tax returns if self-employed, cover the rest.
Lenders compare the proposed payment, and all your monthly debt payments, to your gross income. Many lenders treat total debt payments under about 36% of gross income as manageable and get stricter above roughly 43%, but each sets its own cutoff.
Length of credit history is 15% of a FICO score, so keep your oldest cards open. Each application is a hard inquiry, and myFICO says one extra inquiry costs most people fewer than five points. Auto inquiries inside a rate-shopping window (14 days on older FICO versions, 45 on newer) count as one, and FICO ignores them for the first 30 days.
The CFPB says most negative information stays on your report for seven years and bankruptcies up to ten; Experian puts a repossession at seven years from the first missed payment, Chapter 13 at seven from filing and Chapter 7 at ten. Their weight fades as they age.
You fill out one credit application, we shop it across our dealer network for the lender and program that place you in the best tier, and we deliver the car to your home or office in Los Angeles County.
You never need to visit a dealership; we bring the car to you. In September 2026 the process looks like this.
Approval comes before delivery. California law adds a safety net: the Vehicle Leasing Act requires every lease to state that if your credit application is not approved you may return the vehicle and get your money back (unless you gave incomplete or incorrect information), and bars a lessor from refusing a creditworthy person the advertised price.
You have two routes, raise the score before you apply or structure the lease so a lower tier still works, and many people can do both within a few months.
Programs change every month, so sign up for deal alerts by text and we will text you each month's new specials as they land.
Whatever your score says today, here is how to move forward with us.
Often, yes, but not at the advertised payment. A 650 is near prime by GM Financial's definition, so expect a higher money factor, possibly a security deposit or more due at signing, and a request for proof of income.
Possible but uncommon on a new car: 600 is subprime, and 86% of leases went to prime and super-prime borrowers in Experian's second-quarter 2024 breakdown. A strong co-applicant, more due at signing and a model with a strong lease program can make it work.
A traditional new-car lease is very unlikely at 500, which sits well below the 620 line GM Financial uses for subprime and in what Experian calls deep subprime. A co-applicant or six months of credit repair is the better path.
Not with a score around 700 or more, steady income and no recent car-payment problems; the average lease score was 751 in early 2024, per Experian. It gets harder below 670 because the lender also carries the risk on the car's value at lease end.
There is no fixed number, but about 700 and up with income that supports the payment is generally approved alone; Experian suggests 670 as the floor for favorable terms. Below that, lenders more often ask for a co-applicant, a security deposit or more due at signing.
Only slightly and briefly. myFICO says one extra hard inquiry costs most people fewer than five points, auto inquiries inside a 14- to 45-day window count as one, and FICO ignores them for 30 days. Once you sign, the lease reports as an installment account and on-time payments build your score.
Lenders publish no fixed income minimum; they compare your payment and total debts to your gross monthly income, and the cutoffs vary by lender. Many lenders treat total debt payments under about 36% of gross income as manageable, though each sets its own cutoff; expect to show pay stubs, a W-2 or 1099, or bank statements if self-employed.
Keep reading: the 3 numbers that decide every lease deal and whether to lease or buy a car in Los Angeles.
Sources